Mega GST Certification Course | Recorded Sessions
Build a career in the GST sector with GST Certification Course, led by our team of highly sought-after Top 25 GST Experts - Hurry and Enroll today!
- Trending
- Language : English
- Chapters : 25
- Category : Online Accounting Recorded Courses
- Author : CA Praveen Sharma
WHAT IS GST?
GST stands for “Goods and Services Tax”, and is proposed to be a complete indirect tax levy on the manufacture, sale, and intake of products in addition to offerings on the countrywide level.
The GST certification course may be taken via way of means of graduates, CAs, agency secretaries, economic and tax specialists, and those who need professional possibilities in those fields. It will increase process possibilities, salaries, and development abilities. The GST Certification Courses is offered by the Ministry of MSME (Micro, Small & Medium Enterprises).
The purpose of the course is to assist businessmen, accountants, Chartered Accountants (CAs) Certified Management Accountants (CMAs), Company Secretaries (CSs), and different specialists to decorate their know-how concerning the Goods and Services Tax by offering specialized, update knowledge systematically, enhancing their problem-fixing and analytical abilities to enhance selection making, and imparting skills and knowledge required for self-employment and employment withinside the industry.
Advantages of the GST Certification Course:-
✅It facilitates raising an individual’s income by 15% to 25% on average.
✅It will increase the wide variety of job opportunities available to individuals.
✅ It allows people to begin their personal consultancy.
✅ It facilitates to increase of the abilities of various taxation, finance, and accounting specialists.
Requirements:-
✅ This direction takes you through the fundamentals of GST and turns you into an expert also providing GST Course.
✅ You simply want to have interest earlier than beginning this direction
✅ They Need to have a simple knowledge of taxes and the proper enthusiasm to study taxes
What are the benefits of this course at Academy Tax4wealth:
✅ By enrolling in the GST certification course of Rs. 20,000 at a 60% discount, you gain access to comprehensive recorded video sessions at an unbeatable price of Rs. 8,000, saving Rs. 12,000.
✅ Certificate of participation
✅ The study material will be in PPT format
✅ Details analysis of GST Provisions with the practical aspect
✅ With the help of examples and discussion of practical issues
✅ Coverage of all recent amendments and their Implications.
✅ Learning with 26 Practicing professionals with the real-life issue in GST.
✅ Linking of All sections with relevant rules.
✅ Analysis of open and recent burning issues in GST & recent judgments.
✅ Recorded Sessions
✅ PPT with Details can be downloaded
✅ 180 days of access to recorded videos
✅ Compatible with Mobile, Laptop, and TV
✅ Certificate after Completion
List of GST Experts:
|
14-07-2021 |
Wednesday |
6-8 PM |
Goods & Services Tax (GST) - Overview |
CA. Rajender Arora + CA. Praveen Sharma |
|
|
16-07-2021 |
Friday |
6-8 PM |
Administration |
3-6 |
CA. Kashish Gupta |
|
21-07-2021 |
Wednesday |
6-8 PM |
Levy and Collection of Tax |
7-9 |
CA. Arpit Haldia Ji |
|
23-07-2021 |
Friday |
6-8 PM |
Composition Scheme |
10 |
CA. Mukul Kedia Ji |
|
28-07-2021 |
Wednesday |
6-8 PM |
Exemptions |
11 |
CA. Vishal Poddar Ji |
|
30-07-2021 |
Friday |
6-8 PM |
Time of Supply |
12-14 |
CA. Aanchal Kapoor |
|
04-08-2021 |
Wednesday |
6-8 PM |
Value of Supply |
15 |
CA. Virender Chauhan Ji |
|
06-08-2021 |
Friday |
6-8 PM |
Input Tax Credit |
16-21 |
CA. Rashmi Jain Ji |
|
11-08-2021 |
Wednesday |
6-8 PM |
Registration |
22-30 |
CA. Arup Das Gupta Ji |
|
13-08-2021 |
Friday |
6-8 PM |
Invoice, Credit & Debit Notes and E-Invoice |
31-34 |
CA. Swapnil Munot Ji |
|
18-08-2021 |
Wednesday |
6-8 PM |
Accounts & Records |
35-36 |
CA. Mitesh Doshi |
|
20-08-2021 |
Friday |
6-8 PM |
Returns |
37-48 |
CA. Deepak Bholusaria Ji |
|
25-08-2021 |
Wednesday |
6-8 PM |
Payment of Tax, TDS/TCS |
49-53 |
CA. Gurjeet Singh Bhullar Ji |
|
27-08-2021 |
Friday |
6-8 PM |
Refunds |
54-58 |
CA. Rajender Arora |
|
01-09-2021 |
Wednesday |
6-8 PM |
Assessment |
59-64 |
Adv. Suresh Aggarwal Ji |
|
03-09-2021 |
Friday |
6-8 PM |
Audit |
65-66 |
CA. Shivani Shah |
|
08-09-2021 |
Wednesday |
6-8 PM |
Inspection, Search & Seizure and Arrest |
67-72 |
Adv. Avinash Poddar Ji |
|
10-09-2021 |
Friday |
6-8 PM |
Demand & Recovery |
73-84 |
CA. Vinaymar Gupta Ji |
|
15-09-2021 |
Wednesday |
6-8 PM |
Liability to pay in certain cases |
85-94 |
CA. Abhishek Raja Ram |
|
17-09-2021 |
Friday |
6-8 PM |
Appeals & Revision |
107-121 |
CA. Vikas Golchaa Ji |
|
22-09-2021 |
Wednesday |
6-8 PM |
Offences and Penalties |
122-138 |
CA. Rajesh Khandelwal Ji |
|
24-09-2021 |
Friday |
6-8 PM |
Miscll Provisions- Job Work Procedure, Deemed Export etc |
143-174 |
CA. Praveen Sharma |
|
29-09-2021 |
Wednesday |
6-8 PM |
IGST Act - Sec-7 to 13 |
CA. Archana Jain Ji |
|
|
01-10-2021 |
Friday |
6-8 PM |
E-Way Bill |
CA Venugopal Gella Ji |
|
|
06-10-2021 |
Wednesday |
6-8 PM |
Tools under GST |
CA. Ramya C |
|
|
08-10-2021 |
Friday |
6-8 PM |
Major Case Laws under GST |
CA. Avinash Poddar Ji, CA. Arpit Haldia Ji, CA. Rajesh Khandelwal Ji |
After Sessions, unlimited queries can be asked at our Telegram Group for up to 6 months.
✅ MBA Finance.
✅ LLB practitioners and aspirants
✅ GST Practitioner
✅ Govt.Officials
✅ CA,CS,ICWA
✅ IAS aspirants
✅ CA aspirants
✅ Business Person
Course Meterials
Goods & Services Tax (GST) - Overview with CA. Rajender Arora + CA. Praveen Sharma (Session 1)
26 Days course on GST of 2 hours per session-: 51 Hours of Learning with on demand videos 30 Minutes for Query resolution post each session Details analysis of GST Provisions with practical aspect
Administration By Kashish Gupta (Session 2)
1. Introduction to the Topic 2. Section 3. Officers under CGST Act / SGST Act 3. Section 4. Appointment of Officers 4. Section 5. Powers of Officers 5. Section 5(3). Delegation of Powers 6. Jurisdictional officer working out of jurisdiction 7. Section 6. Authorization of officers of State Act or Union Territory tax as proper officer in certain circumstances 8. An Observation
Levy and Collection of Tax By Arpit Haldia (Session 3)
Section 7(1)(A), Section 7(1)(aa), Section 7(1)(b), Section 7(1)(c), Section 7(1)(1A), Section 7(2), Section 7(3)
Composition Scheme By Mukul Kedia (Session 4)
Composition Scheme (Section 10)
Exemptions By Vishal Poddar (Session 5)
EXEMPT SUPPLIES UNDER GST
Time of supply By Aanchal Kapoor (Session 6)
Goods : 12(1) - What is time of supply of goods ? 12(2) - Liability to pay tax in case of Forward Charge 12(3) - Liability to pay tax in case of Reverse Charge 12(4) - Liability to pay tax in case of issue of Vouchers 12(5) - Residuary category 12(6) - Liability to pay tax in case of special charges due to delayed payment of consideration Services : 13(1) - What is time of supply of services ? 13(2) - Liability to pay tax in case of Forward Charge 13(3) - Liability to pay tax in case of Reverse Charge 13(4) - Liability to pay tax in case of issue of Vouchers 13(5) - Residuary category 13(6) - Liability to pay tax in case of special charges due to delayed payment of consideration
Value of Supply By Virender Chauhan (Session 7)
Valuation of Supply Under GST Section 15 - Value of taxable supply Valuation Rules
Input Tax Credit By Pawan Arora (Session 8)
INPUT TAX CREDIT SECTION 16 AND OTHER IMPORTANT ASPECTS
Registration By Arup Das Gupta (Session 9)
INTRODUCTION BASIC CONCEPT REGISTRATION PROCEDURE CANCELLATION OF REGISTRATION REVOCATION OF REGISTRATION
Invoice, Credit & Debit Notes and E-Invoice By Swapnil Munot (Session 10)
SEC 31(1): TAX INVOICE FOR GOODS SEC 122 / 132: PENALTIES AND PUNISHMENT SEC 31(2): TAX INVOICE FOR SERVICE
Accounts & Records By Mitesh Doshi (Session 11)
Records to be maintained – Sec 35 r/w rule 56 Maintenance of Electronic Records – Rule 57 Records to be maintained by godown/warehouse operators –Rule 58 Period of retention of accounts/records – Sec 36
Returns By Deepak Bholusaria (Session 12)
Section 39 –Key takeaways Return filers
Payment of Tax, TDS/TCS By Gurjeet Singh Bhullar (Session 13)
Sections • 49. Payment of tax, interest, penalty, and other amounts • 49A. Utilization of input tax credit subject to certain conditions • 49B. Order of utilization of input tax credit • 50. Interest on delayed payment of tax • 51. Tax deduction at source • 52. Collection of tax at source • 53. Transfer of input tax credit • 53A. Transfer of certain amounts
Assessment By Suresh Aggarwal (Session 14)
Meaning of “Assessment”- Section 2(11) “Assessment” means a determination of tax liability, and includes self assessment, re-assessment, provisional assessment, summary assessment and best judgment assessment.
Audit By Shivani Shah (Session 15)
Audit – meaning thereof: Section 2(13) “audit” means the examination of records, returns, and other documents maintained or furnished by the registered person under this Act or the rules made thereunder or under any other law for the time being in force to verify the correctness of turnover declared, taxes paid, refund claimed and input tax credit availed, and to assess his compliance with the provisions of this Act or the rules made thereunder
Demand & Recovery By Vinaymar Gupta (Session 16)
• In Pre GST era section 11A of Central Excise Act, section 28 of the Customs Act, and Section 73 of Finance Act 1994 dealt with SCNs • In GST law following sections deal with SCN: a) Section 73: Determination for a reason other than fraud or wilful misstatement or suppression of facts to evade tax b) Section 74: Determination by reason of fraud or wilful misstatement or suppression of facts to evade tax
Liability To Pay In Certain Cases By Abhishek Raja Ram (Session 17)
These provisions of chapter XVI – From Section 85 to 94 – specify the persons, who shall be liable for the payment of GST, in several different situations.
Appeals & Revision By Vikas Golchha (Session 18)
Offences and Penalties By Rajesh Khandelwal (Session 19)
Introduction Definition of Penalty The word penalty is not defined in the GST Law. But in general, it means punishment (Monetary as well as Prosecution) given to a person for some wrongdoing. 3 Few Key Aspects of Penalty Admitting liability to pay tax does not amount to an admission of wrongdoing that can attract penalties in all cases. That is, proceedings are independent of tax demand. An important change that can be seen in the GST law, as compared to erstwhile laws is that now the Government does not seem to give discretionary powers to the officers for imposing penalties.
Refunds By Kashish Gupta
Miscll Provisions- Job Work Procedure, Deemed Export etc By Praveen Sharma
GSTR-9 Annual Return Practical Session 22
Get GST-9 annual return course providing a practical video in which you learn all the modules in a brief lesson. this session is going to be very useful for you. Download to self-study.
GST Filing Annual Returns Practical By Praveen Sharma (Session 23)
GSTR-9 is the annual return to be filed by taxpayers registered under GST. this session is going to be very useful for you.
GST Annual Return GSTR-9 Under GST Practical BY Praveen Sharma (Session 24)
File GSTR-9 Annual Return BY CA Praveen Sharma (Session 25)
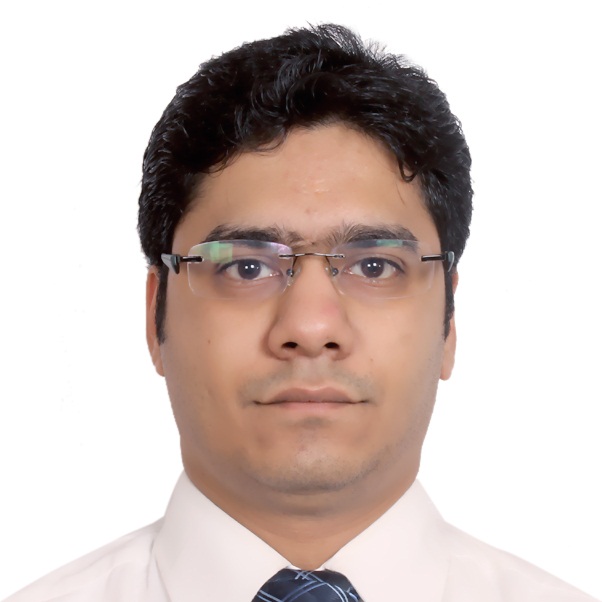
CA Praveen
GST and Indirect Tax Laws Expert
CA. Praveen Sharma is a qualified Chartered Accountant with rich experience in Industry Taxation, Budgetary and MIS. He is well versed with Industrial Laws and has over the years acquired proficiency in Indirect Tax Laws and in the Implementation of an effective accounting and control procedure.
He is a recognized faculty of The Institute of Chartered Accountants of India for Indirect Taxes. He addressed Certificate and Advance Courses of ICAI and Other Institutes on GST, besides addressing Study Circles and other forms of trade and professionals.
He has provided GST training to Officers of 32 States and Union Territories and to CBIC Officers.
He is the Master Trainer at GSTN and organized a residential program, for about three weeks, for the training of CBEC and VAT Officers of various states at the Chennai Campus of Infosys.
Book an AppointmentGet in touch
Related Courses
Get in touch